Real deals. Real results.
We don't just talk about speed and certainty — here's the evidence. Every case study is a real deal with real numbers, showing exactly how we helped where others couldn't.
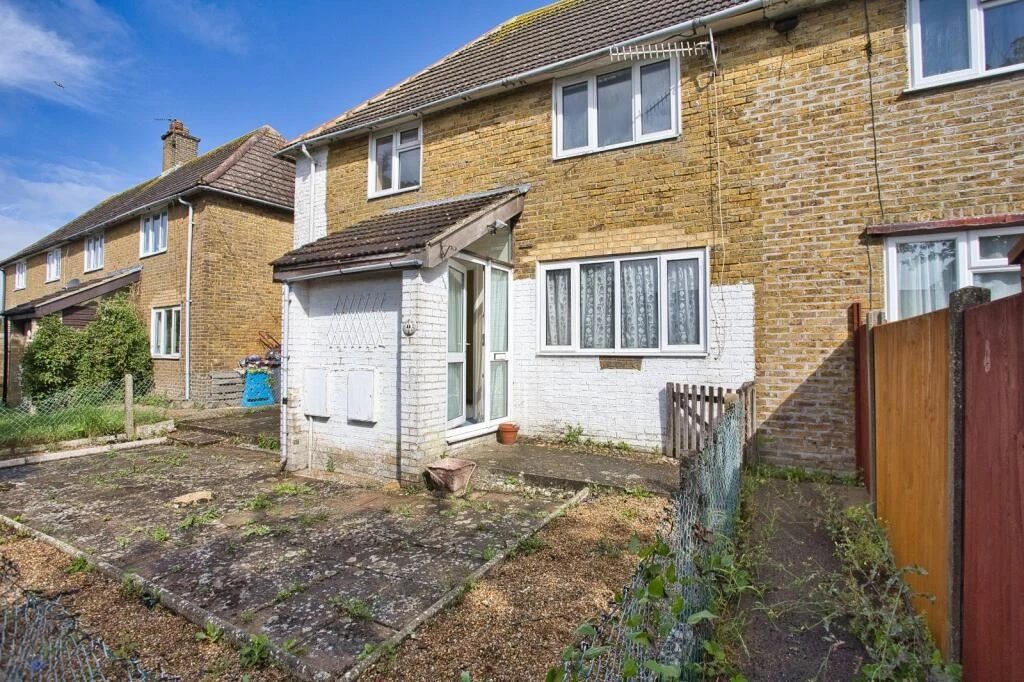
DIP Inside 24 Hours. Same Price Ten Weeks Later.
Modern Method of Auction purchase at 75% of the auction price, held at the quoted terms while the seller's side caught up.
A limited company reserved a semi-detached house in Dover at £160,000 through the Modern Method of Auction and needed evidence of funding for the platform within a day. Terms went out the same morning and the decision in principle inside 24 hours. The seller's solicitor then took ten weeks over enquiries — and the facility completed on exactly the terms quoted in July.
Read the case study →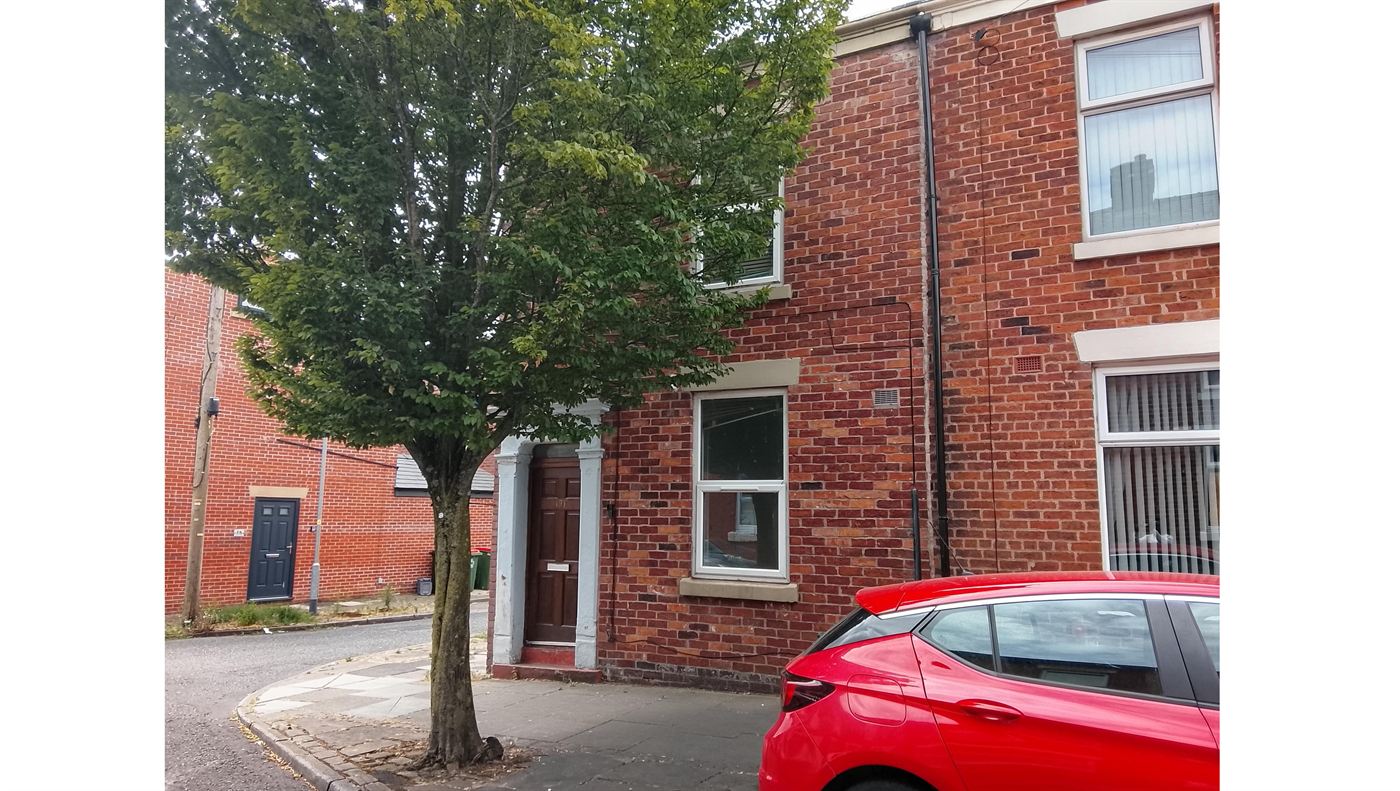
Lease in Dispute on the Title. Terms in 42 Minutes.
Auction purchase funded encumbered — tenant, lease and rent dispute all left in place.
A freehold end-terrace taken at auction with a 25-year social housing lease and a live rent dispute on the title. Another specialist lender gave indicative terms, read the legal pack and declined at application stage. AF Credit asked two questions and issued written terms 42 minutes after the first email, accepting the lease position up front and funding the property exactly as it stood.
Read the case study →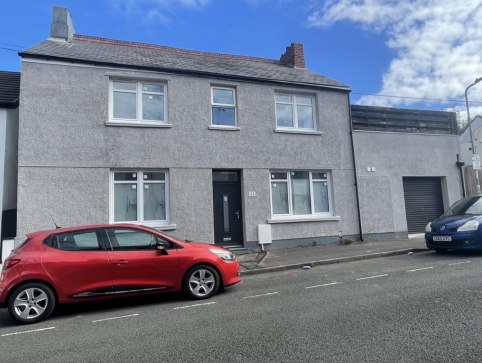
Another Lender Took a Month and Walked. We Completed in 17 Days.
Rebridge against a hard redemption deadline. No valuation, internal inspection and our own residual calculation.
A Newport borrower needed to refinance an existing bridging facility before a fixed redemption date. Another lender had held the case for a month, reached legals and withdrawn over the property's planning history. An existing valuation had been instructed on the wrong basis. AF Credit instructed no valuation, inspected internally, ran its own residual calculation and completed a day before the deadline.
Read the case study →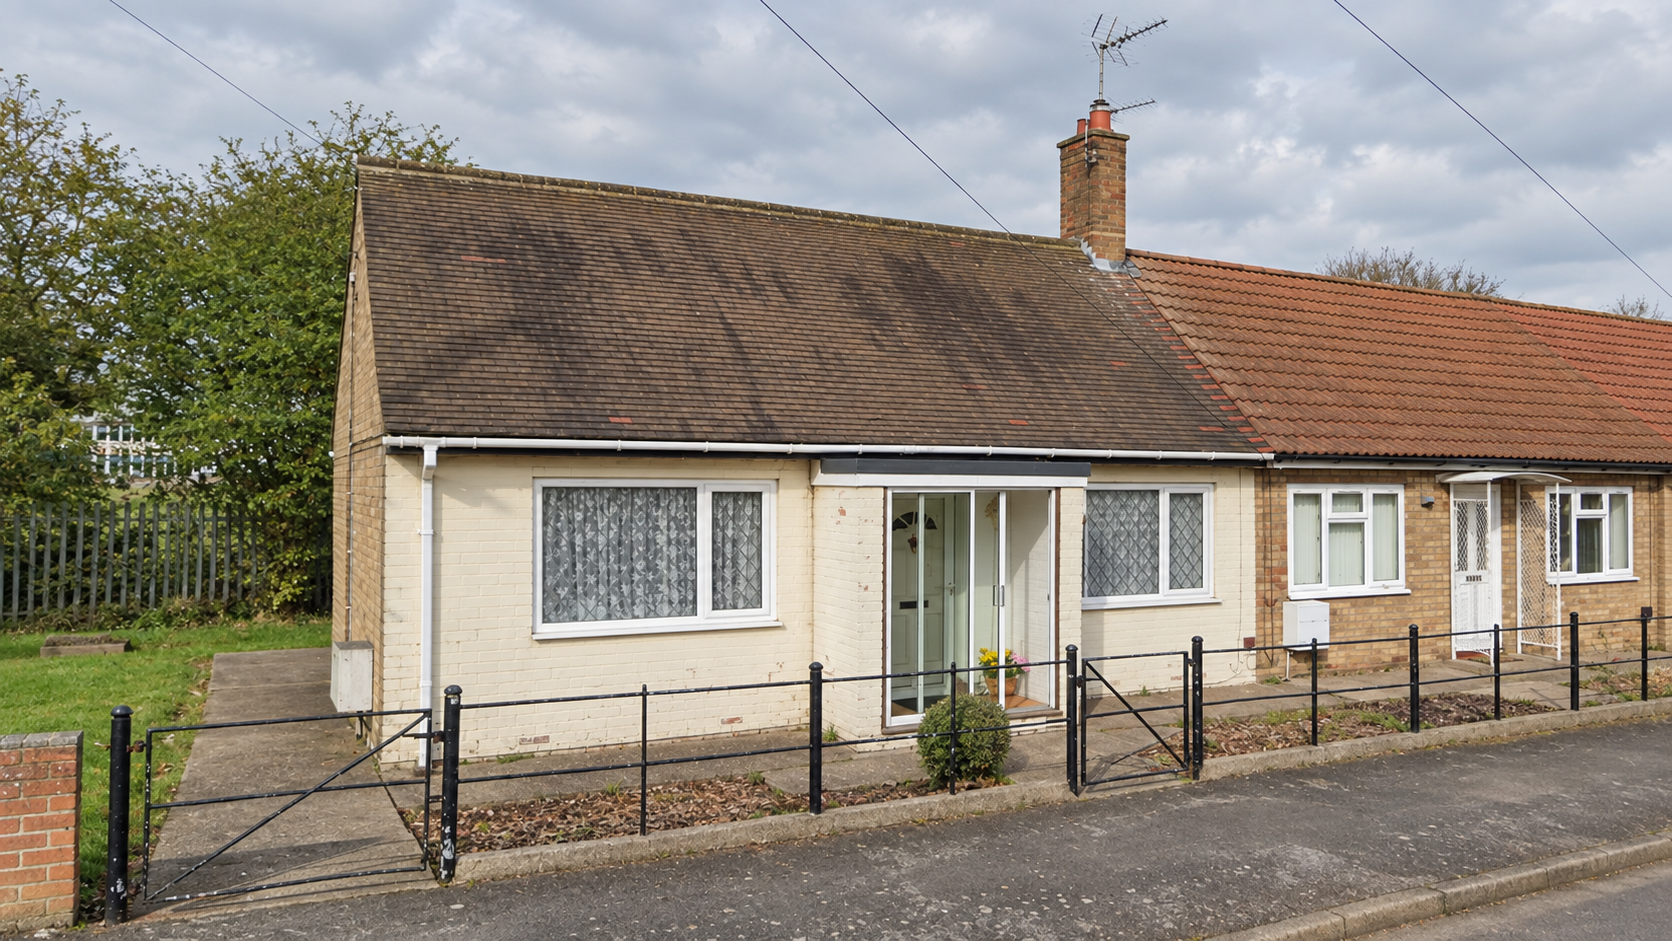
Adverse Credit. Hard Deadline. £6,600 Already at Risk. Completed in 16 Days.
Ltd company contractor, MMA purchase. Non-status asset-led lending. AVM, all costs rolled, zero upfront fees.
Ltd company contractor with adverse credit needed to complete an MMA bungalow purchase in Hull by a hard deadline — £6,600 reservation fee already at risk. Previous lenders had failed to deliver. AF Credit issued same-day terms, used an AVM, rolled all costs and completed on the contractual deadline.
Read the case study →
£130,000 Against a Director's Main Residence. No Surveyor Visit.
Ltd company borrower, third-party first charge on the director's home. Desktop valuation, 23.3% gross LTV, 12 months retained interest.
A limited company needed to release capital for business use. The only available security was the director's personal main residence in Palmers Green, North London. AF Credit structured a third-party first charge with a desktop valuation — no surveyor visit, no monthly payments, 12-month term to arrange refinance.
Read the case study →
Three Below-Market Apartments. No Valuations. No Delay.
Five-property portfolio used as security. 61.8% gross LTV, £0 valuation cost, 12-month term. Purchase completed before the opportunity was lost.
Three apartments purchased at £60,000 each — well below market value. Two existing short-term let properties offered as additional security. AF Credit assessed all five properties without a single site visit, completing a portfolio-backed bridging loan at 61.8% gross LTV.
Read the case study →
£620,000 Against a Commercial Showroom. No New Valuation Required.
Existing evidence, internal assessment, 44% LTV. Borrower completed a residential purchase before the opportunity was lost.
Commercial vehicle showroom, 7,395 sq ft, Mottingham. New 15-year lease, £121,000 annual rent, 14-month rental guarantee. AF Credit assessed internally — no new survey, no delay. Borrower secured a residential investment in Chigwell against the clock.
Read the case study →
£210,000 HMO Bridging Loan. Two-Bed to Five-Bed Conversion.
Former local authority house, Cambridge. 57.8% LTV, £550k GDV, £51k estimated annual rent. Mainstream lenders declined.
Experienced property company converting a 2-bed former council house into a 5-bedroom HMO. Full conversion — 4 bathrooms, ensuite kitchenettes, garage extension. Mainstream lenders declined. AF Credit structured the refurbishment bridge at 57.8% LTV with a clear refinance or sale exit.
Read the case study →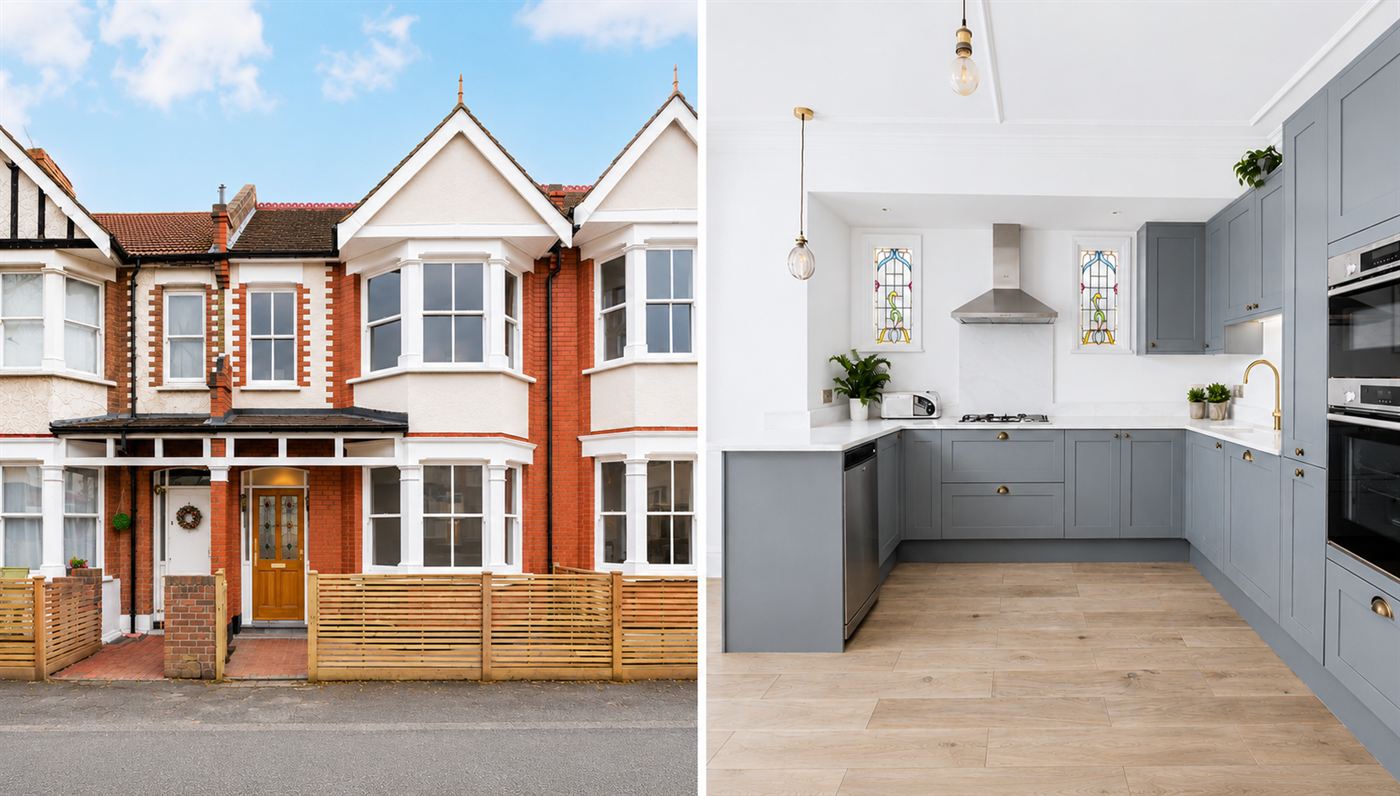
Bridge Expiring. Buyer Renegotiating. Default Interest Looming.
Penge refurbishment flip under offer. AF Credit provided a £485,000 no valuation bridging loan — desktop valuation only, default interest avoided.
Bought £475k, refurb £150k, sold £825k — £200k gross profit. But the sale didn't complete in time. AF Credit refinanced the existing bridge at 65% LTV with desktop valuation only, avoiding default interest. Contractor restriction resolved via solicitor undertaking.
Read the case study →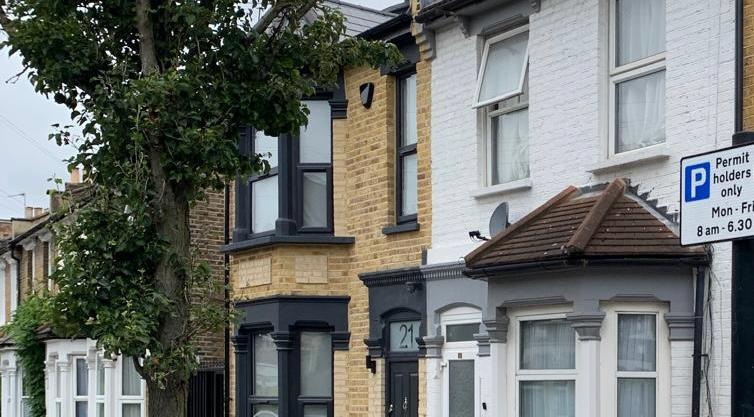
Existing Lender Refused to Extend. Completed in 10 Days.
Refurbished East London residence. Rebridge at full post-works value — no survey, no searches, hard deadline met.
Existing bridging lender refused to extend with a hard deadline looming. AF Credit rebridged at full post-works value — no valuation, no-search indemnity, completed in 10 working days.
Read the case study →
First-Time Buyer. Non-Standard Construction. Completed in 15 Days.
Detached cottage, gifted equity deposit, desktop valuation only. AF Credit completed where standard lenders declined.
First-time buyer, non-standard construction cottage, gifted equity from family. Standard lenders declined. AF Credit structured a desktop valuation bridging loan at 57.8% LTV — purchase completed in 15 days with a clear refinance exit.
Read the case study →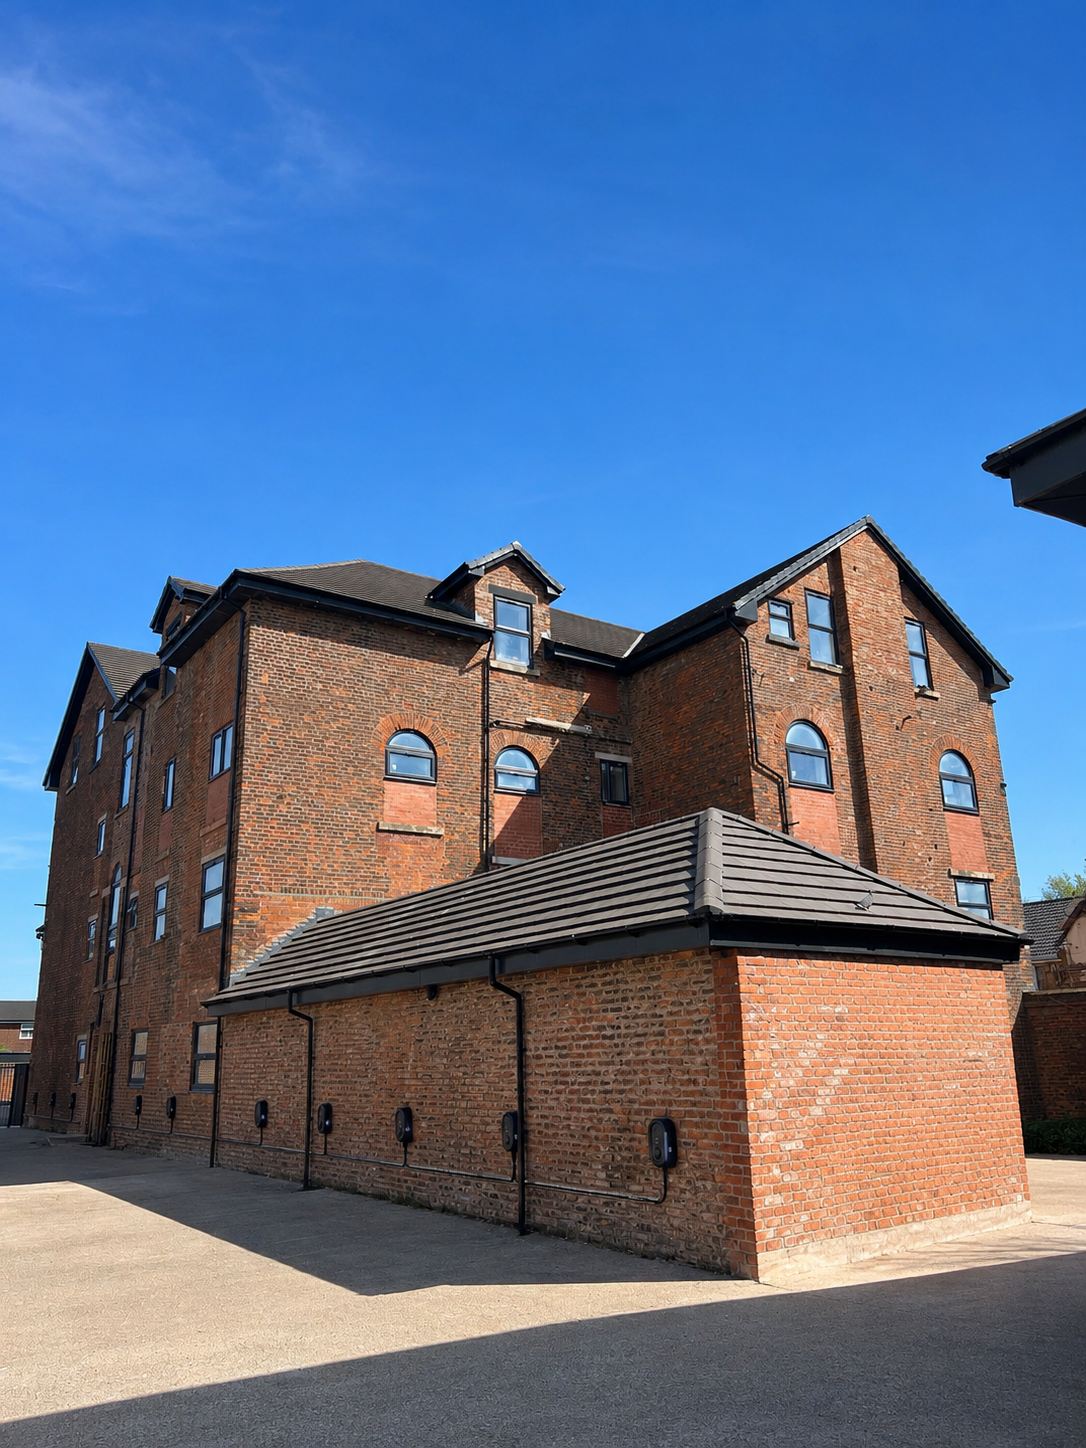
Multiple Lenders Declined. AF Credit Completed.
21-unit commercial-to-residential conversion. No valuation, no build warranty at drawdown, second fix stage.
Developer needed capital to complete second fix on a 21-unit Manchester conversion. Multiple lenders declined due to build stage, no warranty and no valuation. AF Credit structured a £325,000 facility at 35% LTV against the £3.9m GDV.
Read the case study →
£1,000,000 Raised. No New Valuation Required.
Prime gated Surrey residence. Existing RICS report audited and accepted — no surveyor instructed, no valuation fees, no delays.
An experienced developer needed rapid capital to fund a time-sensitive London commercial opportunity. A two-year-old RICS report was already on file. AF Credit audited it, accepted it, and completed — without instructing a single surveyor.
Read the case study →
Two CCJs. Mortgage Declined. Completed in 18 Days.
Two satisfied CCJs, historic arrears, high-street lender declined. AF Credit completed at 50% LTV in 18 days with a BTL refinance exit.
Harborne, Birmingham semi-detached. Two satisfied CCJs (3–4 years old) plus historic mortgage arrears. High-street BTL lender declined. AF Credit provided a 12-month bridge at 50% LTV — exit planned for BTL refinance as CCJs aged past the 4-year threshold.
Read the case study →
Semi-Commercial Auction. Completed 6 Days Inside the Deadline.
Shop with flat above, Coventry. 57.8% blended LTV. Specialist RICS blended valuation. 22 days from enquiry to completion.
Shop with tenanted flat above, purchased at auction in Coventry for £450,000. 28-day completion window. Specialist RICS blended valuation. AF Credit completed in 22 days — 6 days inside the deadline — with a semi-commercial investment mortgage refinance exit.
Read the case study →
£38,000 Refurbishment. GDV £290,000. Sold at £289,500.
Victorian mid-terrace, Beeston. 75% LTV, 9-month term, 14 days to complete. Capital fully recycled.
Victorian mid-terrace purchased for £205,000 in Beeston, Nottingham. £38,000 refurbishment — kitchen, bathroom, rewiring, windows. GDV £290,000–£300,000. Sold at £289,500. Bridge completed in 14 days; investor's capital fully recycled.
Read the case study →
Inheritance Tax Due. Probate Not Yet Granted. 12 Days.
Sole executor, £190,000 IHT liability, desktop valuation at 32% LTV. AF Credit unlocked the estate in 12 days.
Detached 4-bedroom house, Sherborne, Dorset valued at £875,000. Executor needed £190,000 to pay HMRC before probate granted. Property unsellable until grant issued. AF Credit completed at 32% LTV using desktop valuation in 12 days. Sold at £862,000 post-probate.
Read the case study →
Mortgage Lender Withdrew Day 14. Completed Day 21.
Original BTL mortgage lender cited property condition on day 14 of 28. AF Credit stepped in at 75% LTV and completed in 7 days.
End-of-terrace, Wolverhampton, purchased at auction for £118,000. BTL lender withdrew on day 14 citing condition (no kitchen, boiler requiring replacement). AF Credit has no minimum condition standard — stepped in at 75% LTV and completed in 7 working days.
Read the case study →
Buyer Pulled Out Day Before Exchange. Completed in 5 Days.
Chain break, Redland Bristol flat. AVM valuation, no-search indemnity, 60% LTV. Onward purchase preserved.
Vendor's buyer withdrew 24 hours before exchange. Onward purchase at risk. AVM valuation (same day, £0) plus no-search indemnity removed the two longest delays. £207,000 at 60% LTV completed in 5 working days. Flat re-sold at £350,000 nine weeks later.
Read the case study →
10 Days Left. Completed in 9.
First-time BTL investor's deposit rescued after original lender withdrew 18 days in.
Savills auction purchase — original lender pulled out with the deadline looming. AVM valuation, gifted deposit cleared, dual rep legals. Completed one day inside the extended deadline.
Read the case study →