Specialist Bridging Finance · Direct Lender

Direct bridging loan lender
£5k–£2m, from 0.79%.

We lend our own capital, so one underwriter reads your case and decides it. AVM cases run to 65% LTV with no valuation fee; a desktop valuation takes you to 75% without a surveyor visit.
75% LTVMaximum LTV
0.79%Monthly rates from
£5k–£2mLoan range
Same dayIndicative terms
Direct principal lender We lend our own funds Same-day formal terms No early repayment charge Brokers & introducers welcome England & Wales
Compare our lending

Our bridging products at a glance

Every product below is funded and underwritten by AF Credit directly — these are our own lending terms, not a panel or a marketplace. All lending is unregulated, secured on investment property in England and Wales.

ProductRates fromMax LTVLoan sizeTypical speed
Residential BridgingChain breaks, capital raises, unmortgageable stock 0.79%per month 75%£5k–£2m7–14 working days View
Auction FinanceBuilt for the 28-day completion deadline 0.79%per month 75%£5k–£2m5–10 working days View
Refurbishment FinanceLight to heavy refurb, staged drawdowns 0.79%per month 75% day one£5k–£2m10–15 working days View
Semi-CommercialShop with flat above, mixed-use assets 0.79%per month 70% blended£100k–£2m2–4 weeks View
Commercial BridgingOffice, retail, industrial, mixed-use 0.99%per month 65%£100k–£2m2–4 weeks View
Adverse Credit BridgingCCJs, defaults and arrears assessed on merit Case by case 70%£5k–£2m7–14 working days View

Swipe the table sideways to see every column →

How to read this table

LTV (loan to value) is the loan as a percentage of the property's value — a £300,000 property at 70% LTV supports a £210,000 loan. Rates from are monthly, not annual, and apply to the strongest cases; your actual rate depends on LTV, property type, term and the strength of your exit. Typical speed assumes clean title and a responsive solicitor.

Beyond the monthly rate there is an arrangement fee, legal fees and an exit fee. See the full cost breakdown.

Run your own figures with the bridging loan calculator, or see the full breakdown on our rates page.

Why AF Credit?

One underwriter.
No committee.

AF Credit lends its own capital. The person who reads your case is the person who decides it, and they stay on it through to completion.

We lend on investment property in England and Wales — unregulated bridging only, so nothing secured on a borrower's own home. Within that, we underwrite the asset and the exit rather than a scorecard.

1

Terms the same day

Indicative terms the day you enquire. On qualifying cases legals are instructed within 12 hours of the credit decision.

2

One named underwriter

The same person from the first call to completion. No case-handler relay and no external credit committee.

3

England and Wales

Residential, semi-commercial and commercial. First charge, vacant or tenanted, individuals or SPVs.

4

No valuation, still 75%

AVM is free and instant to 65% LTV. A desktop valuation is around £425 and takes you to 75% — no surveyor visit either way.

Bridging loans explained

What is a
bridging loan?

A bridging loan is short-term finance, typically lasting 3 to 24 months, secured against a property or other asset. It bridges a gap — between buying and selling, or between now and long-term finance.

1

Short-term — 3 to 24 months

Designed to last only as long as you need before your exit strategy completes.

2

Interest added to your loan

In most cases interest is rolled up and repaid at the end, keeping monthly outgoings to zero.

3

Secured against property

Your property may be at risk if the loan is not repaid within the agreed term.

Our process

From enquiry to funds.
In days, not weeks.

1

Same-day response

Tell us your situation and we'll provide indicative terms the same day. No waiting on committees.

2

One decision maker

A single underwriter owns your case from start to finish. Direct access, clear answers.

3

Legals within 12 hours

Once your application is approved we can instruct solicitors and progress to completion fast.

About AF Credit

Reliable decisions.
Fast execution.
Certainty when it matters most.

We lend our own funds and make every decision in-house. No external committees, no third-party sign-off — just experienced people moving quickly.

  • ✓  Own capital — no reliance on external funding lines
  • ✓  Real people, not a call centre
  • ✓  National appetite across England and Wales
  • ✓  Dual representation legals available
75%Max LTV
12 hrsInto legals
0.79%Rates from
£2mMax loan
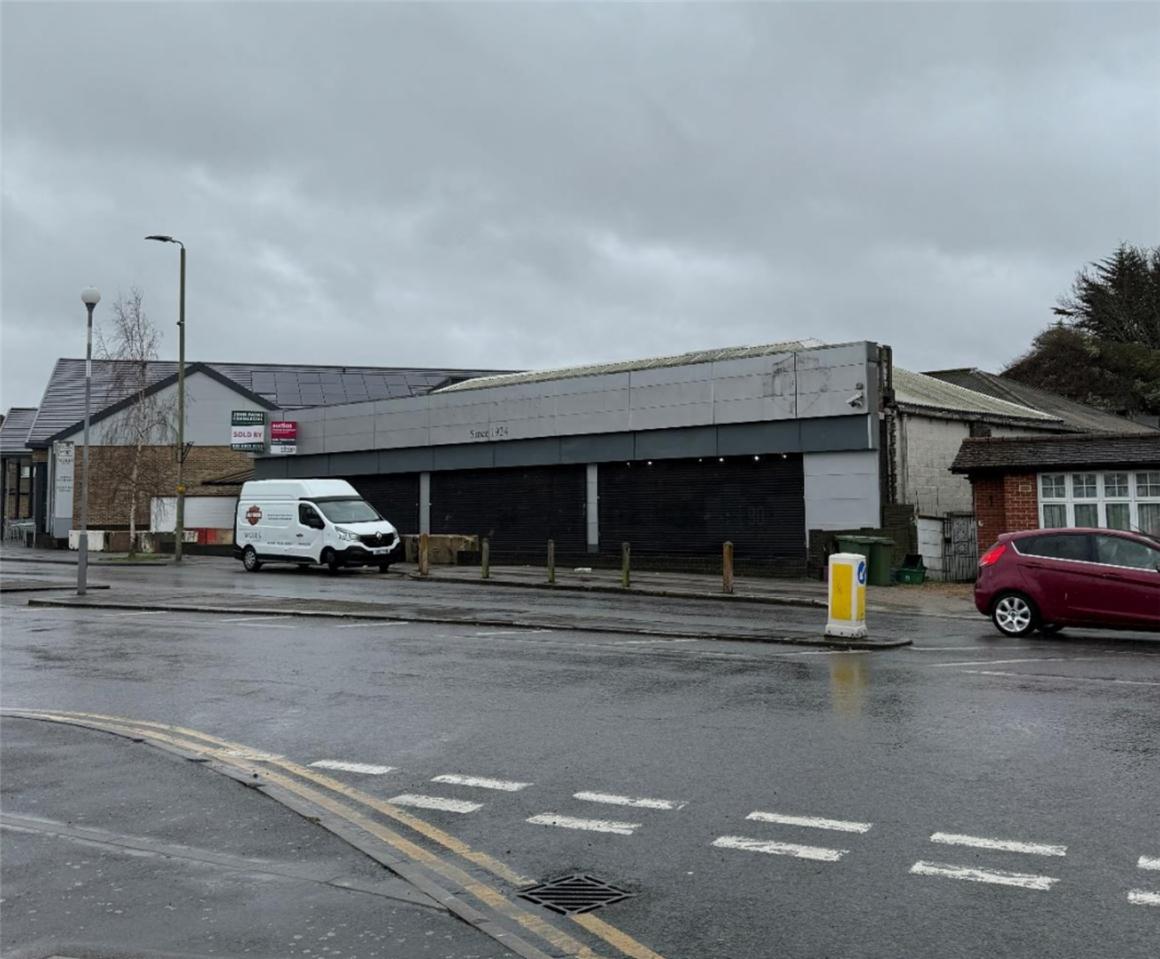
Commercial vehicle showroom, South East London: no valuation bridging loan case study
Case study

£620,000 Against a Commercial Showroom

South East London. No new valuation, 44% LTV. Read the case study →

Common questions

Everything you need to know.

We lend from £5,000 to £2 million, up to 75% LTV on residential property. Commercial and semi-commercial LTV is assessed case-by-case.

We provide same-day indicative terms on straightforward cases. Formal offers and legal instruction can follow within 24–48 hours, with completion often possible within 5–10 working days.

Not always. Eligible properties can use AVM (automated valuation model) or desktop valuation options, removing the need for a physical survey and saving both time and cost.

We lend on residential (including uninhabitable), commercial (offices, retail, industrial), semi-commercial (mixed-use), and development sites across England and Wales.

Yes. We lend to individuals, limited companies, LLPs and SPVs. Offshore structures are considered on a case-by-case basis.

At our maximum 75% LTV you need at least 25% of the property value as equity or deposit, plus transaction costs — stamp duty, legal fees and the arrangement fee. On a £400,000 property that means £100,000 of equity plus costs. Lower LTVs typically attract lower rates, so contributing more can reduce what you pay.

Four components: monthly interest (from 0.79%), an arrangement fee of 2–3% of the gross loan, valuation (£0 on AVM cases), and legal fees for both sides. An exit fee of one month's interest is payable on redemption. There is no early repayment charge, though a three-month minimum interest period applies. Our costs guide works through real examples, and the calculator gives you a figure in seconds.

A mortgage is long-term finance for a property you intend to hold, and takes weeks to months to arrange. A bridging loan is short-term (3–24 months), completes in days, and is repaid from a defined exit — usually a sale or a refinance onto a mortgage. If you need speed, or the property is currently unmortgageable, bridging is the tool. See our full comparison guide.

Your exit is how the loan gets repaid — typically selling the property, or refinancing onto a mortgage or buy-to-let. It is the single most important part of any bridging application. We assess whether your exit is realistic and achievable within the term before we lend, because a credible exit protects you as much as it protects us.

Usually not. Most borrowers either roll interest up (it accrues and is settled at redemption) or have it retained (deducted from the advance upfront). Both mean zero monthly outgoings during the term. Serviced interest, where you pay monthly, is available if you prefer to preserve the full loan amount.

Yes. There is no early repayment charge. If your sale or refinance completes ahead of schedule you can redeem straight away — a three-month minimum interest period applies, and an exit fee of one month's interest is payable on redemption. There is no long lock-in.

No. AF Credit provides unregulated bridging finance only, secured on investment and commercial property. We cannot lend where you or a close family member lives in, or intends to live in, the security property. All of our lending is to businesses and property professionals on investment assets.

Send the property address, loan amount, purpose and proposed exit and we will come back the same day with formal terms. You deal directly with the underwriter throughout, your client relationship is protected, and procuration fees are confirmed at terms stage and paid on completion. Full details on our intermediaries page.

Proof, not promises

Real deals. Real results.

Every case study is a live deal with real numbers — see exactly how we helped where another lender couldn't.

📍 North Leeds · Auction Rescue

10 Days Left. Completed in 9.

First-time BTL investor's deposit rescued after their original lender withdrew with 10 days to the deadline. AVM valuation, same-day terms, dual-rep legals.

Read the case study →
£40,500Loan
75%LTV
9Days to complete

View all case studies →

Flexible finance to support you

Ready to talk?

Whether you're a first-time borrower or an experienced investor, our experts are here to help you move with speed and certainty.